The landscape of business taxation is undergoing its most significant transformation in a generation. Making Tax Digital (MTD), the flagship government initiative designed to modernize the UK tax system, is fundamentally changing how sole traders, small and medium-sized enterprises (SMEs), and landlords interact with Her Majesty's Revenue and Customs (HMRC). For decades, the annual ritual of gathering paper receipts, logging invoices into spreadsheets, and submitting a single, end-of-year tax return was the standard operating procedure for millions of independent businesses. However, as the digital economy expands, HMRC is enforcing a shift toward real-time, digital record-keeping. Understanding the practical, operational, and financial implications of Making Tax Digital is no longer optional for business owners; it is an absolute necessity for compliance and continued commercial viability.
To comprehend the full weight of Making Tax Digital, one must first look at the core mechanics of the policy. At its heart, MTD rests on three foundational pillars: mandatory digital record-keeping, the use of MTD-compatible software to submit tax updates, and a move away from annual reporting toward more frequent submissions. For VAT-registered businesses, the first phase of this transition has already been implemented, requiring them to keep digital records and submit VAT returns using specialized software. However, the upcoming and arguably more disruptive phases target sole traders and SMEs who fall under Income Tax Self Assessment (ITSA) and Corporation Tax frameworks. The implications of these changes stretch far beyond simple administrative updates, touching software budgets, internal workflows, and the very relationship businesses have with their financial data.
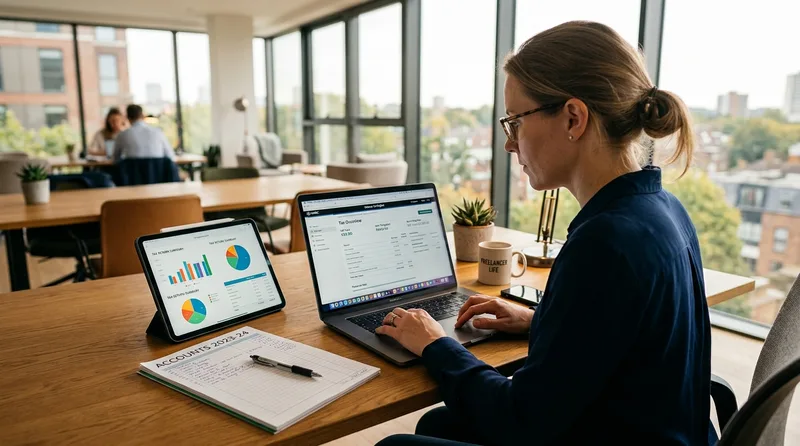
One of the most immediate implications for sole traders and SMEs is the retirement of traditional record-keeping methods. The days of shoeboxes overflowing with paper receipts, handwritten ledger books, and basic, unlinked desktop spreadsheets are numbered. Under MTD regulations, businesses must maintain their records in a digital format. For many micro-businesses and sole traders who have operated successfully for years using analog methods, this represents a steep and sometimes intimidating learning curve. Transitioning to digital record-keeping requires investing in HMRC-compatible software. While many software packages offer intuitive user interfaces designed for non-accountants, the initial setup phase demands time, patience, and often a financial outlay for subscription fees. Business owners must evaluate their current technological capabilities and decide whether to adopt cloud-based accounting solutions such as Xero, QuickBooks, Sage, or HMRC-approved bridging software that connects existing spreadsheets to the government gateway.
Beyond the software investment, the shift in reporting frequency is arguably the most impactful operational change brought by Making Tax Digital. Historically, sole traders and self-employed individuals dealt with HMRC once a year, calculating their profits and liabilities long after the tax year had closed. MTD for Income Tax Self Assessment (ITSA) changes this dynamic entirely by introducing quarterly updates. Under the new rules, sole traders and landlords with a qualifying income above a certain threshold must submit a summary of their business income and expenses to HMRC every three months. In addition to these four quarterly updates, businesses must submit an end-of-period statement (EOPS) and a final declaration to reconcile their accounts and calculate the final tax due. This quarterly cadence implies a continuous, year-round engagement with tax affairs rather than a frantic annual scramble. While this real-time approach can help businesses maintain a clearer, more accurate picture of their cash flow and tax liabilities as they accrue, it also increases the administrative burden and frequency of interaction with the tax authorities.
The financial implications for sole traders and SMEs are multifaceted. On the positive side, adopting modern digital accounting tools can lead to greater financial visibility. Real-time data entry allows business owners to spot cash flow bottlenecks early, track overdue invoices more effectively, and make informed strategic decisions based on up-to-date financial metrics. Furthermore, HMRC argues that digital record-keeping reduces the margin for human error, which historically led to costly mistakes, underpaid tax penalties, or accidental overpayments. Accurate, digitized data streamlines the entire tax submission process, theoretically reducing the time spent on year-end accounts.
However, the financial downsides cannot be ignored. The cost of compliance is a genuine concern for many cash-strapped SMEs and sole traders operating on tight margins. These costs include purchasing software subscriptions, upgrading computer hardware, and potentially paying higher accountancy fees. Accountants will likely need to spend more time helping clients adjust to new systems, migrate historical data, and manage quarterly submissions, which may translate to increased advisory and compliance bills for businesses. For smaller sole traders who previously managed their own taxes independently without professional help, the complexity of MTD may force them to hire an accountant for the first time, introducing a new, recurring business expense.
Another critical implication of Making Tax Digital involves data security and digital literacy. As businesses migrate their sensitive financial records to cloud-based platforms, the importance of robust cybersecurity measures increases exponentially. Business owners must ensure they are using secure passwords, enabling multi-factor authentication, and choosing reputable software providers compliant with UK data protection regulations. Furthermore, the varying levels of digital literacy among business owners mean that the implementation timeline will not be uniform. Older sole traders or those operating in rural areas with poor broadband connectivity may face distinct barriers to adoption, raising concerns about digital exclusion and the disproportionate stress placed on non-tech-savvy entrepreneurs.
HMRC has recognized these challenges, leading to phased rollouts and delayed implementation dates to give businesses and software developers adequate time to prepare. For instance, MTD for ITSA has faced multiple postponements to ensure the infrastructure is robust and that taxpayers are not overwhelmed. However, postponement does not mean cancellation. The trajectory is firmly set toward a fully digital tax ecosystem. Sole traders and SMEs must view this transition not merely as a bureaucratic hurdle imposed by the government, but as an inevitable modernization of the business environment. Embracing digital tools proactively rather than reactively will cushion the blow of compliance and position businesses to reap the operational benefits of automation.
In conclusion, Making Tax Digital represents a fundamental paradigm shift for sole traders and small-to-medium enterprises across the United Kingdom. By replacing archaic paper trails and annual reporting with real-time digital record-keeping and quarterly updates, the initiative aims to minimize tax gaps caused by avoidable errors and bring the tax system into the twenty-first century. While the implications include undeniable challenges—such as initial software costs, a steeper learning curve, increased administrative frequency, and potential adjustments to accountancy fees—the long-term advantages of enhanced financial visibility, reduced errors, and streamlined processes are significant. For sole traders and SMEs, the key to navigating this transition successfully lies in early preparation, selecting the right digital tools, and maintaining open communication with financial advisors. Those who adapt swiftly to the requirements of Making Tax Digital will not only ensure compliance with HMRC regulations but will also build more resilient, transparent, and digitally empowered businesses for the future.
Comments
No comments yet. Be the first to share your thoughts.
Join the conversation
Log in to leave a comment on Summit Chartered Accountants.